
The Invisible Number: How Credit Dictates Your Life
A few years ago, I walked into an apartment leasing office feeling totally confident, only to get rejected because of a low credit score I didn't even know I had. That embarrassing moment woke me up to the harsh truth of how much power a simple three-digit number holds over our daily lives. I spent months making silly mistakes before I finally figured out how the credit rules actually work. If you feel stuck or stressed about your rating right now, trust me, I have been in your shoes and you can turn things around.
Imagine finding the perfect apartment to rent. You can already picture where your couch will go and how you will decorate the kitchen.
You fill out the application with a smile, confident that everything is fine. A few days later, you get a cold, polite email saying your application was rejected.
The landlord did not even look at your income or your steady job history. They only looked at a single three-digit number on a screen.
This is the hard reality that millions of people face every single day. A low credit score acts like an invisible lock on the doors of your life.
It prevents you from buying a reliable car, getting a low-interest credit card, or even setting up utilities without a massive deposit. It feels like you are being judged by a computer program that does not know your name or your story.
You are far more than a simple number, but the financial system does not care about your hard work or your good intentions. This constant rejection builds a wall of stress that can make you feel completely stuck in place.
- Confusing financial jargon: Most articles use words that sound like they require a law degree to understand.
- Bad advice from social media: You might hear that closing old accounts is good, when it actually hurts your history.
- The trap of quick fixes: Shady companies promise to wipe your record clean overnight for a high fee, which is a scam.
- No school education on money: Most of us were never taught how loans work, leaving us to learn through painful mistakes.
- Vague explanations from banks: Lenders reject people without explaining the real math behind their decision.
- Constant financial anxiety: You live with the fear that your card will be declined at the grocery store check-out.
- Feeling like a total failure: A low score makes you feel bad with money, even if your debt came from a medical emergency.
- A feeling of helplessness: It feels like the big credit bureaus have all the power, and you have none.
- Tension in your relationships: Money stress is one of the main causes of arguments at home with the people you love.
- Avoiding new opportunities: You stop applying for better things because you are too tired of hearing the word "no."
This struggle is exhausting, but you do not have to let this number control your life. Once you learn the simple rules of the game, you can start making the system work for you.
Before we dive into the details, I want to clarify one quick thing: this guide specifically focuses on the United States credit scoring system.
If you are living or planning to build your financial life in the US, these rules apply directly to you. Even if you are based in another country,
many of these core concepts are highly similar, but the exact bureaus and math we are discussing today are tailored specifically to the US market. Let's make sure we are on the same page before we start!
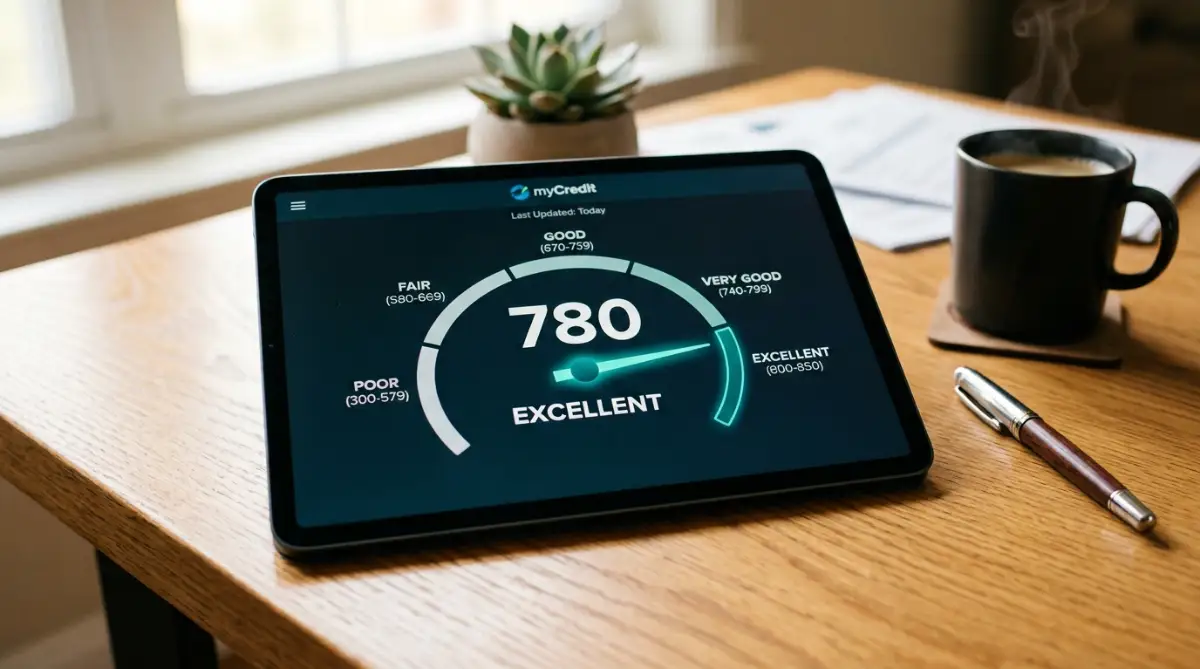
What is a Credit Score and Why Does It Matter?
Think of a credit score like a financial report card. In school, your grades showed teachers how well you studied and completed your homework.
In the financial world, this three-digit number tells banks how well you pay back borrowed money. It is a quick way for lenders to decide if you are a safe bet or a risky gamble.
The system uses your past financial behavior to predict what you will do in the future. If you always pay your bills on time, your score goes up.
If you miss payments or run up huge debts, your score drops down. It is a simple math formula, but it carries a massive amount of power over your daily life.
Want a clear visual walkthrough of how credit scores work and how to boost yours fast? Check out this excellent, in-depth video guide below to master the system and supercharge your score today!
Meet the Three Main Credit Bureaus
Before we look at the numbers, you need to know who is keeping track of your history. Your score does not come from the government.
It comes from three private companies known as credit bureaus. These companies are Equifax, Experian, and TransUnion.
These bureaus collect your payment data from banks, credit card companies, and court records. They do not decide if you get approved for a loan.
They simply gather the facts and put them into a long report. Lenders then buy these reports to see if they want to do business with you.
Sometimes, your score might be slightly different at each of the three bureaus. This is normal because some banks only report your payments to one or two of them.
To make this easy for you, I’ve broken down the key differences between FICO and VantageScore. Here’s a quick comparison of the two main scoring models we use today: